Read a real study before you buy one.
A single-family rental in Sugar Land, Texas, written from 42 photographs and the study form. No closing statement or assessor record was uploaded, so the land value is the 15% default and the review notes say so first. Everything below is as delivered.
First year with SegFlow: 5 / 7 / 15-year classes with 100% bonus depreciation, remainder straight-line over 27.5-year, mid-month. Without: straight-line over 27.5-year on the whole depreciable basis, mid-month convention (month 9). Accelerated share 19.3% of depreciable basis. Federal treatment only.
Four pages of the sample study PDF: Cover, Method and reconciliation, Schedule, Evidence.
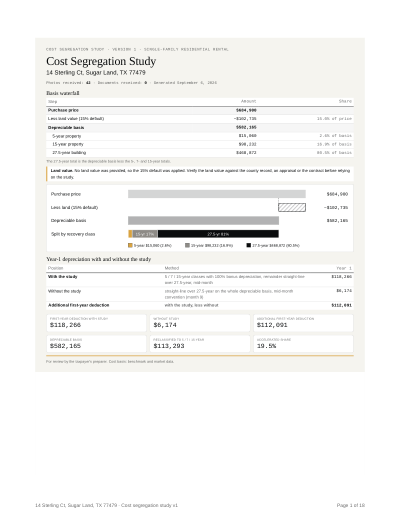
| Class | Lines | Basis allocated | Share |
|---|---|---|---|
| 5-year | 11 | $15,344 | 2.6% |
| 15-year | 12 | $96,697 | 16.6% |
| 27.5-year | 39 | $470,124 | 80.8% |
| Depreciable basis | 62 | $582,165 | 100.0% |
| Component | Quantity | Class | Authority | Basis allocated |
|---|---|---|---|---|
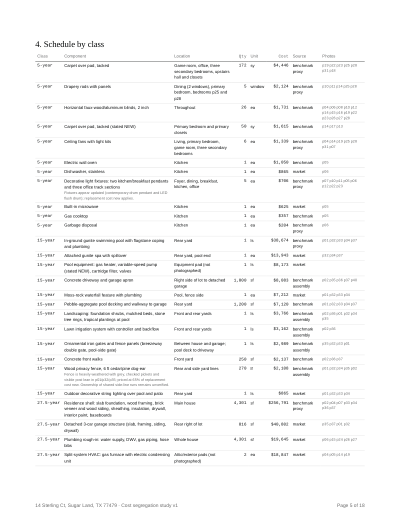
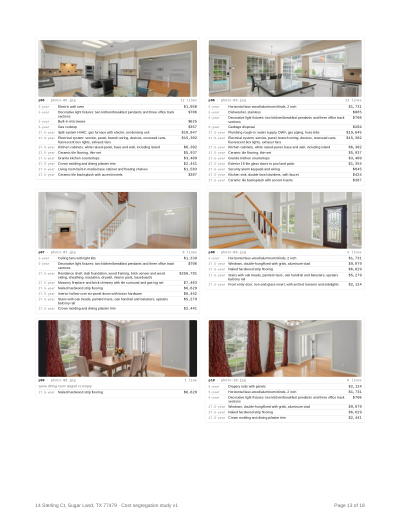
| Carpet over pad, tackedseen in p19, p22, p23, p25, p28, p31, p18 | 172 sy | 5-yr | §1245 | $4,602 |
| Drapery rods with panelsseen in p10, p11, p14, p25, p28 | 5 window | 5-yr | §1245 | $2,198 |
| Horizontal faux-wood/aluminum blinds, 2 inchseen in p04, p06, p08, p10, p12, p14, p15, p16, p19, p22, p23, p26, p27, p28 | 26 ea | 5-yr | §1245 · Hospital Corp. of America | $1,791 |
| Carpet over pad, tacked (stated NEW)seen in p14, p17, p13 | 50 sy | 5-yr | §1245 · Rev. Proc. 87-56 class 57.0 | $1,672 |
| In-ground gunite swimming pool with flagstone coping and plumbingseen in p01, p32, p33, p34, p37 | 1 ls | 15-yr | Rev. Proc. 87-56 class 00.3 | $40,036 |
| Attached gunite spa with spilloverseen in p32, p34, p37 | 1 ea | 15-yr | Rev. Proc. 87-56 class 00.3 | $12,125 |
| Concrete driveway and garage apronseen in p02, p35, p36, p37, p40 | 1,800 sf | 15-yr | Rev. Proc. 87-56 class 00.3 | $8,369 |
| Residence shell: slab foundation, wood framing, brick veneer and wood siding, sheathing, insulation, drywall, interior paint, baseboardsseen in p02, p04, p07, p33, p34, p36, p37 | 4,301 sf | 27.5-yr | §1250 | $265,848 |
| Detached 3-car garage structure (slab, framing, siding, drywall)seen in p35, p37, p01, p32 | 816 sf | 27.5-yr | §1250 | $35,481 |
| Plumbing rough-in: water supply, DWV, gas piping, hose bibsseen in p06, p15, p24, p26, p27 | 4,301 sf | 27.5-yr | Reg. §1.48-1(e)(2) | $17,083 |
The full schedule, with the evidence note and pricing basis for every line, is in the PDF and the Excel ledger. 18 items seen and excluded are listed with reasons.
What to check before you sign.
Verify items first, ordered by effect on the result. 20 notes in all; the first 10 are here, every one is in the PDF.
- No written binding contract date was provided; the closing date (September 5, 2025) was used as the acquisition date for the bonus depreciation rate. Confirm that no binding contract was signed on or before January 19, 2025.
- Pull the 2025 Fort Bend CAD land/improvement split before relying on any class total.
- Use type is assumed long-term residential rental (average stay over 7 days), which sets the building and all structural lines at 27.5-year; if the property is operated as a short-term rental the building becomes 39-year and furnishings would enter the study.
- Acquisition 2025-09-05 is carried from intake, not a closing statement; confirm the closing date, the binding-contract date and the date the unit was first available for rent, because 100% bonus depreciation applies to the 5- and 15-year classes only if the binding contract was signed after January 19, 2025 and the property was placed in service in 2025 (otherwise the 40% phase-down rate applies).
- Purchase price $684,900, 4,301 sf and 1989 year built were not document-verified; a different contract price or a seller-paid closing-cost credit changes the basis and every class total proportionally.
- Obtain the non-realty items addendum and the closing statement's personal-property allocation: it settles whether the two refrigerators (removed), the plug-in string lights, the basketball goal and the drapery panels conveyed; each reinstatement or removal moves 5-year or 15-year basis directly.
- The pool, spa, waterfall and decking (about $65,000 before rescale) are the dominant 15-year driver.
- Lowest-confidence lines: bldg-shell (0.5, index covers only two of the shell trades so $68.50/sf is market data), hvac (0.45), water-heaters (0.4), security-system (0.4), string-lights (0.4) and pool (0.5, 1989 shell priced at replacement cost new with a small-project factor). None except the pool materially moves an accelerated class.
- Coverage gaps: left side elevation, full rear elevation, garage interior, attic and pool equipment pad were not photographed; window and exterior door counts on those faces are inferred, garage door openers are not lined (about $800 if present) and no powder room is assumed.
- No Form 3115 is needed if the property is first placed in service by this taxpayer in 2025 and this study is used on the 2025 return. If depreciation was already claimed on a prior-year return, an automatic change (DCN 7) with a §481(a) adjustment is required instead of amending.
Inputs. 42 photographs and 0 documents were received for 14 Sterling Ct, Sugar Land, TX 77479. The price used is the purchase price as entered on the study form (closing costs and capital improvements not included): $684,900. Land value: 15% of the purchase price (default; no land value was provided), $102,735. Depreciable basis: $582,165.
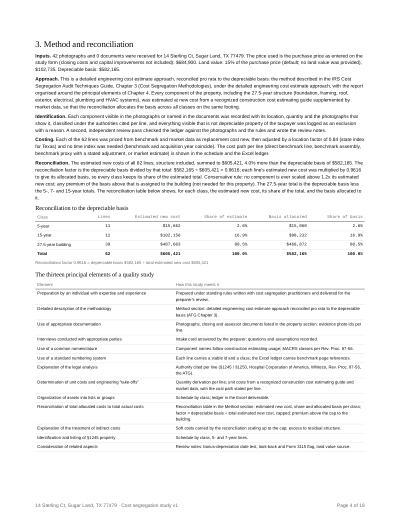
Approach. This is a detailed engineering cost estimate approach, reconciled pro rata to the depreciable basis: the method described in the IRS Cost Segregation Audit Techniques Guide, Chapter 3 (Cost Segregation Methodologies), under the detailed engineering cost estimate approach, with the report organised around the principal elements of Chapter 4. Every component of the property, including the 27.5-year structure (foundation, framing, roof, exterior, electrical, plumbing and HVAC systems), was estimated at new cost from a recognized construction cost estimating guide supplemented by market data, so that the reconciliation allocates the basis across all classes on the same footing.
Identification. Each component visible in the photographs or named in the documents was recorded with its location, quantity and the photographs that show it, classified under the authorities cited per line, and everything visible that is not depreciable property of the taxpayer was logged as an exclusion with a reason. A second, independent review pass checked the ledger against the photographs and the rules and wrote the review notes.
Costing. Each of the 62 lines was priced from benchmark and market data as replacement cost new, then adjusted by a location factor of 0.84 (state index for Texas) and no time index was needed (benchmark and acquisition year coincide). The basis on which each line was priced is stated with the line in the Excel ledger, alongside the authority for its classification. Documented costs. Where a document supplied for this study states what a component cost, that figure is used as the estimate for the component and the document is cited on the line. For an acquired property the taxpayer's basis is the purchase price, so a documented cost is evidence of the value of that component relative to the others rather than the taxpayer's basis in it; the allocation still reconciles to what the taxpayer paid, and both figures are shown: the documented cost as given and the allocated basis after reconciliation.
Reconciliation. The estimated new costs of all 62 lines, structure included, summed to $696,217, 19.6% more than the depreciable basis of $582,165. The reconciliation factor is the depreciable basis divided by that total: $582,165 ÷ $696,217 = 0.8362; each line's estimated new cost was multiplied by 0.8362 to give its allocated basis, so every class keeps its share of the estimated total. Conservative rule: no component is ever scaled above 1.2x its estimated new cost; any premium of the basis above that is assigned to the building (not needed for this property). The 27.5-year total is the depreciable basis less the 5-, 7- and 15-year totals. The reconciliation table below shows, for each class, the estimated new cost, its share of the total, and the basis allocated to it.
This study was prepared with software assistance and is provided for the preparer's review and professional judgment; it has not been reviewed by an engineer. Classifications follow the authorities cited per line; the preparer should confirm the use type and any facts flagged under Verify in the review notes. Federal treatment only. State conformity, passive-activity limits and recapture on disposition are outside the scope. Uploaded files are retained for 12 months from upload, then deleted; the preparer should download and keep their own copies. This report, the ledger and the review notes are retained with the study.
Study generated September 8, 2026; acquisition September 5, 2025; property at 14 Sterling Ct, Sugar Land, TX 77479.
Run one on your own property.
Email admin@segflowai.com for 50% off your first study. Residential or light commercial and multifamily, delivered in under an hour.